|
FRIEND OF FRIEND
/ THE WEEKLY
|
VOL. 09
· 2026
|
FRIEND.
RISK-INTELLIGENCE FOR SMALL-BUSINESS INSURANCE
· VOL. 09, WEEK OF OCTOBER 05, 2026
· 5-MINUTE READ
Insurance prices you by the bucket you land in. Friend's goal is to make those buckets smaller and more precise.
|
LAST TIME WE SAID
|
Vol. 08: the industry is starting to pay real money to tell one building from the next. This week we show the picture of why that is worth paying for.
|
|
FROM THE DESK
We are going to try something a little different this week. Instead of a development to react to, the lead is an explainer: one chart, the one the whole company rests on. The short version is this. Insurance cannot price your business on its own, so it drops you into a bucket with businesses that look like you and charges everyone in the bucket the same price. Run yours well and you are the cheap member of an expensive band, quietly paying for the neighbor who never fixed the stairs. The Buckets is the picture of that gap, and closing it is the entire reason Friend exists. The three briefs below are the market inching toward the same idea from three directions. Tell me if the explainer format earns its place, or if you would rather we keep the lead on the news.
NEWCOMBE · FOUNDER, FRIEND · NEW YORK
|
THIS WEEK · THE ONE TO DISCUSS
|
THE EXPLAINER · FIG. 01
|
|
Illustrative example · drawn to explain the idea, not real data
The whole argument, in three charts.
|
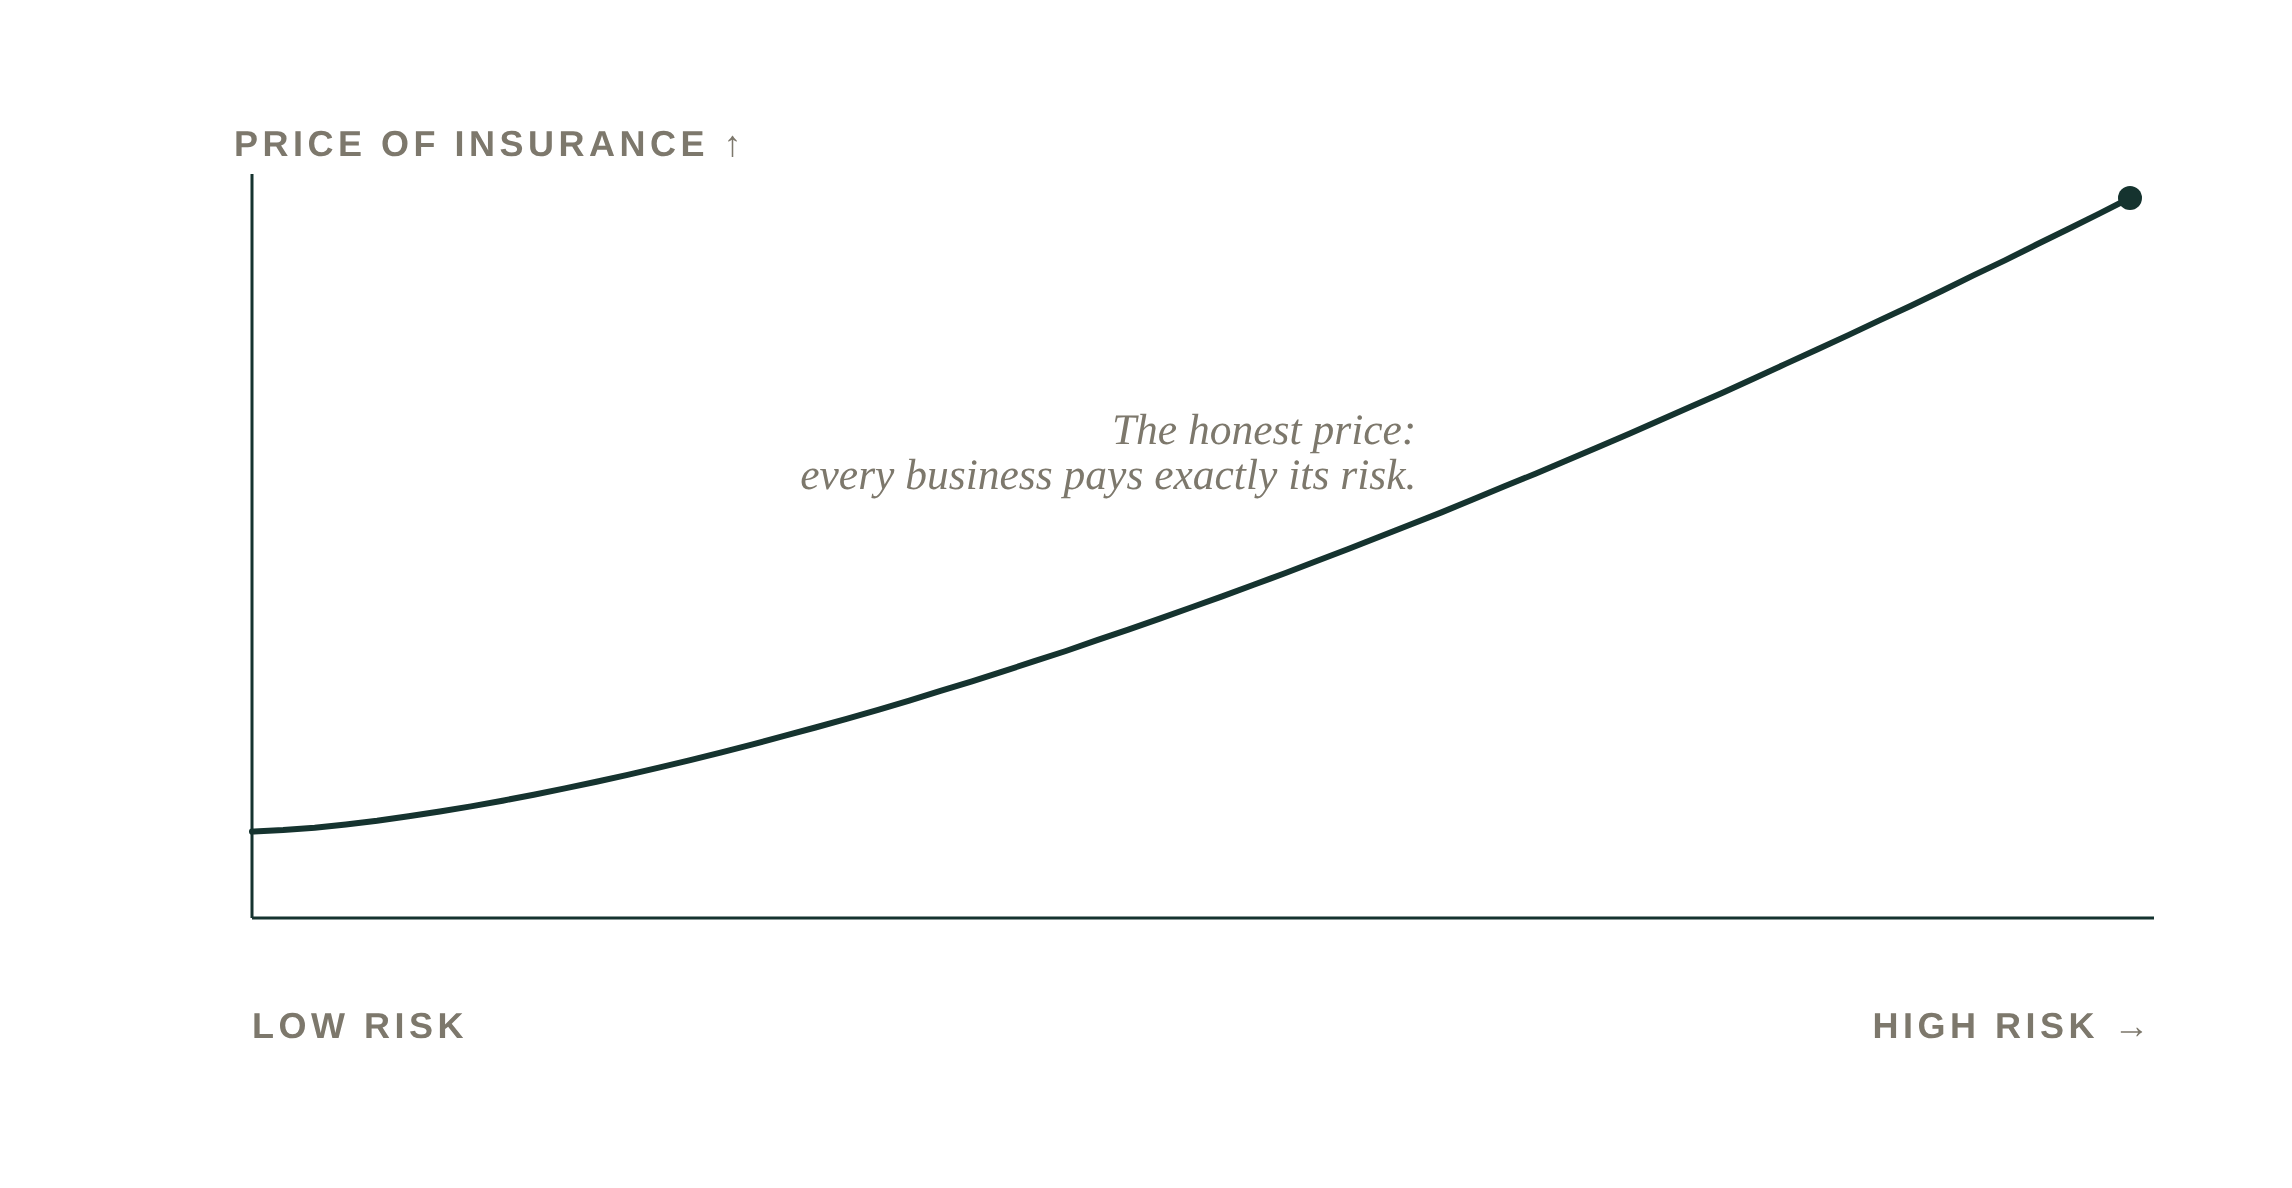
01 · In theory
Price follows risk.
The honest price is one smooth line: more risk, a little more premium. Nobody can draw it for a real bar or bakery.
|
|
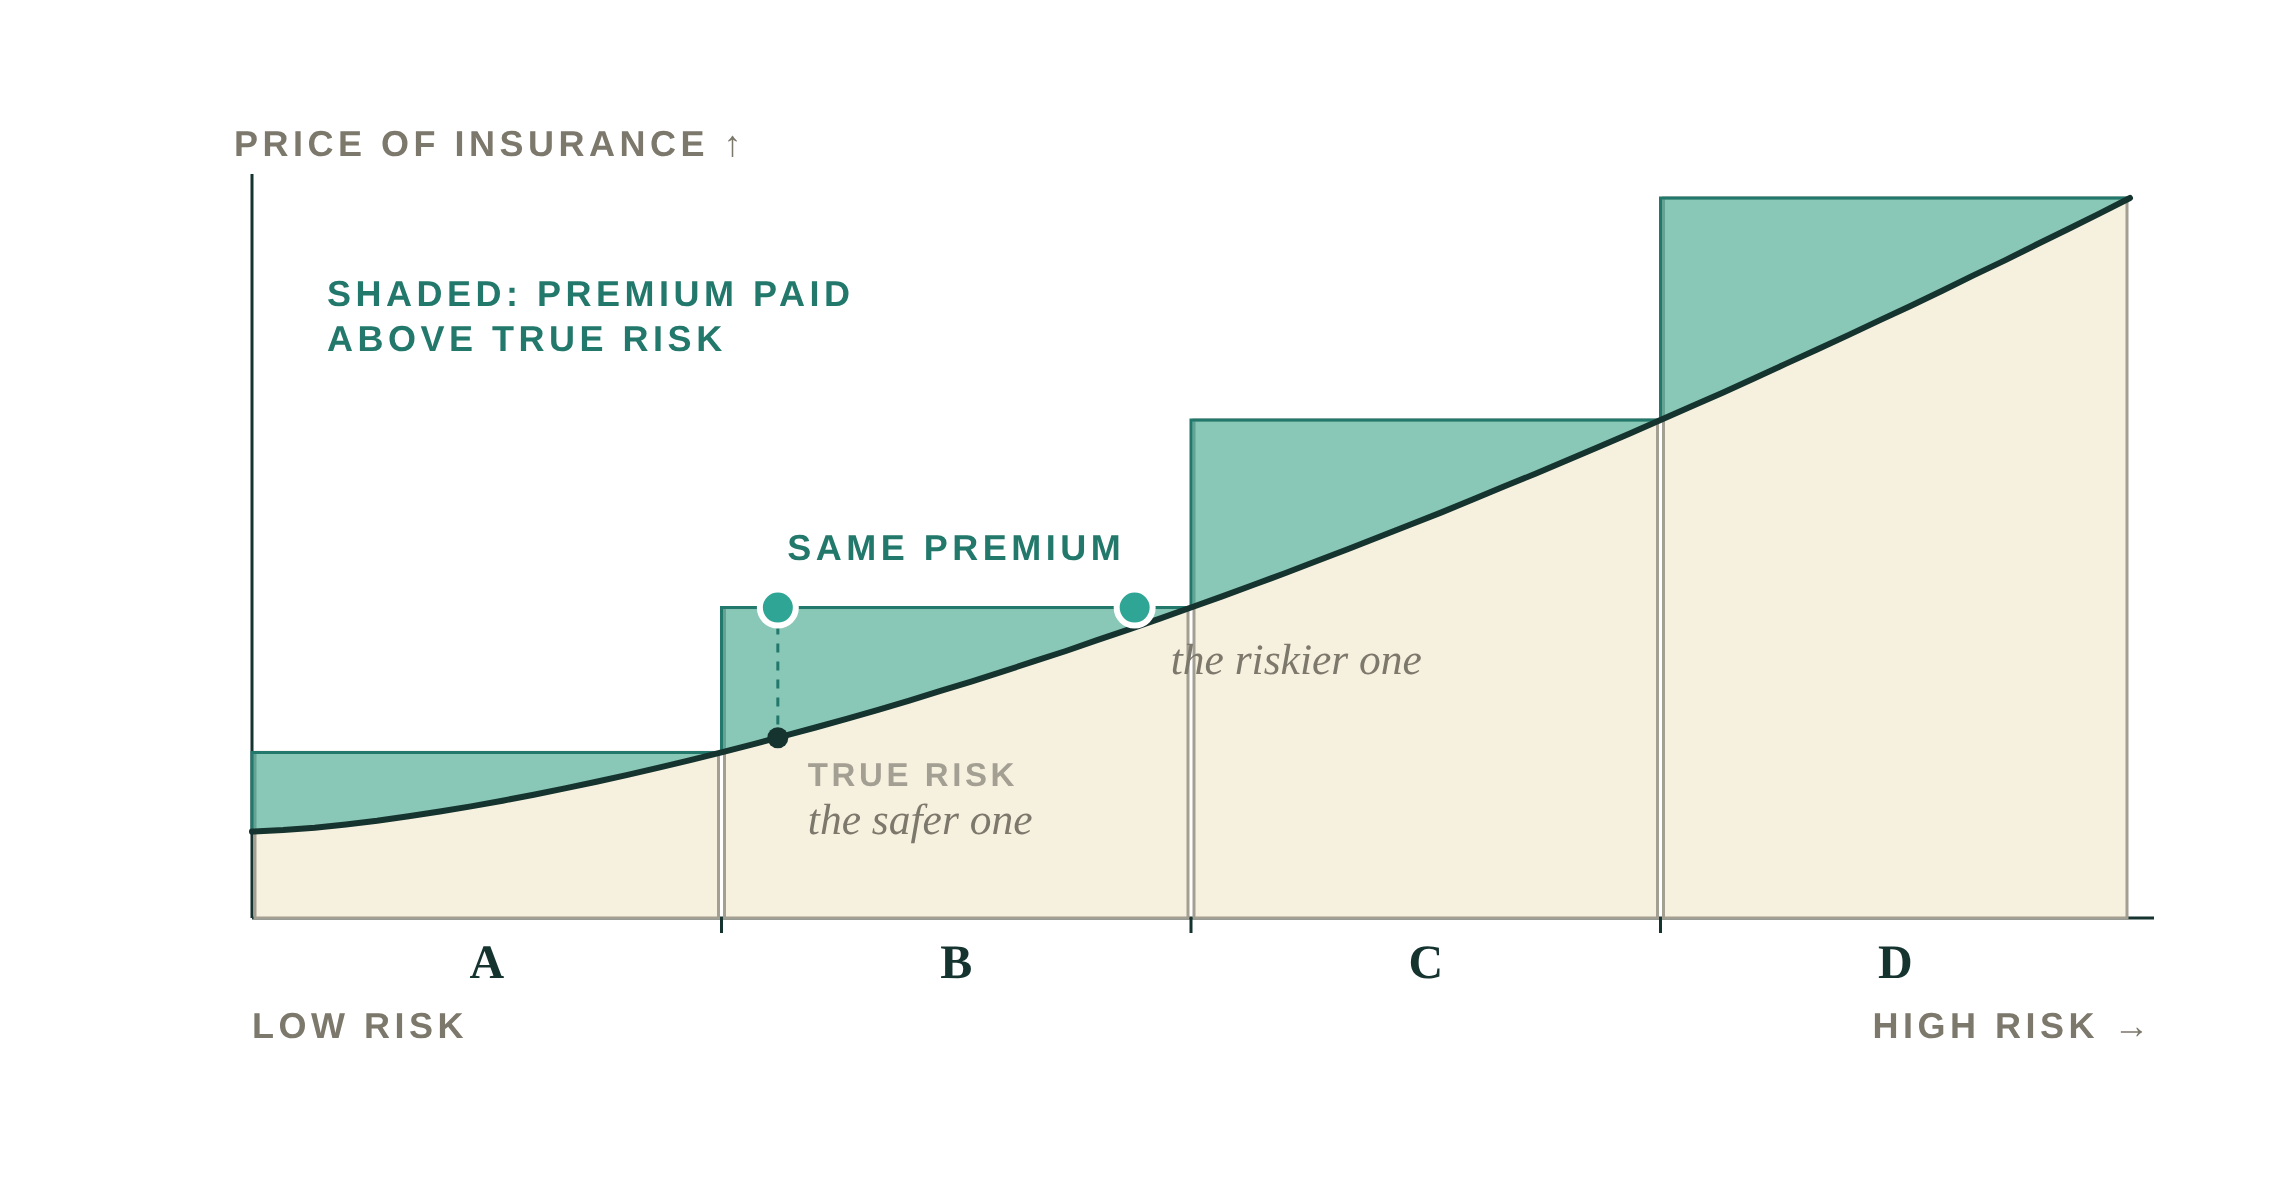
02 · In practice
You are priced by the bucket.
Carriers drop you into one of four bands off three inputs and charge everyone the band's price, set by its riskiest member. The safer business overpays the shaded gap, every renewal.
|
|
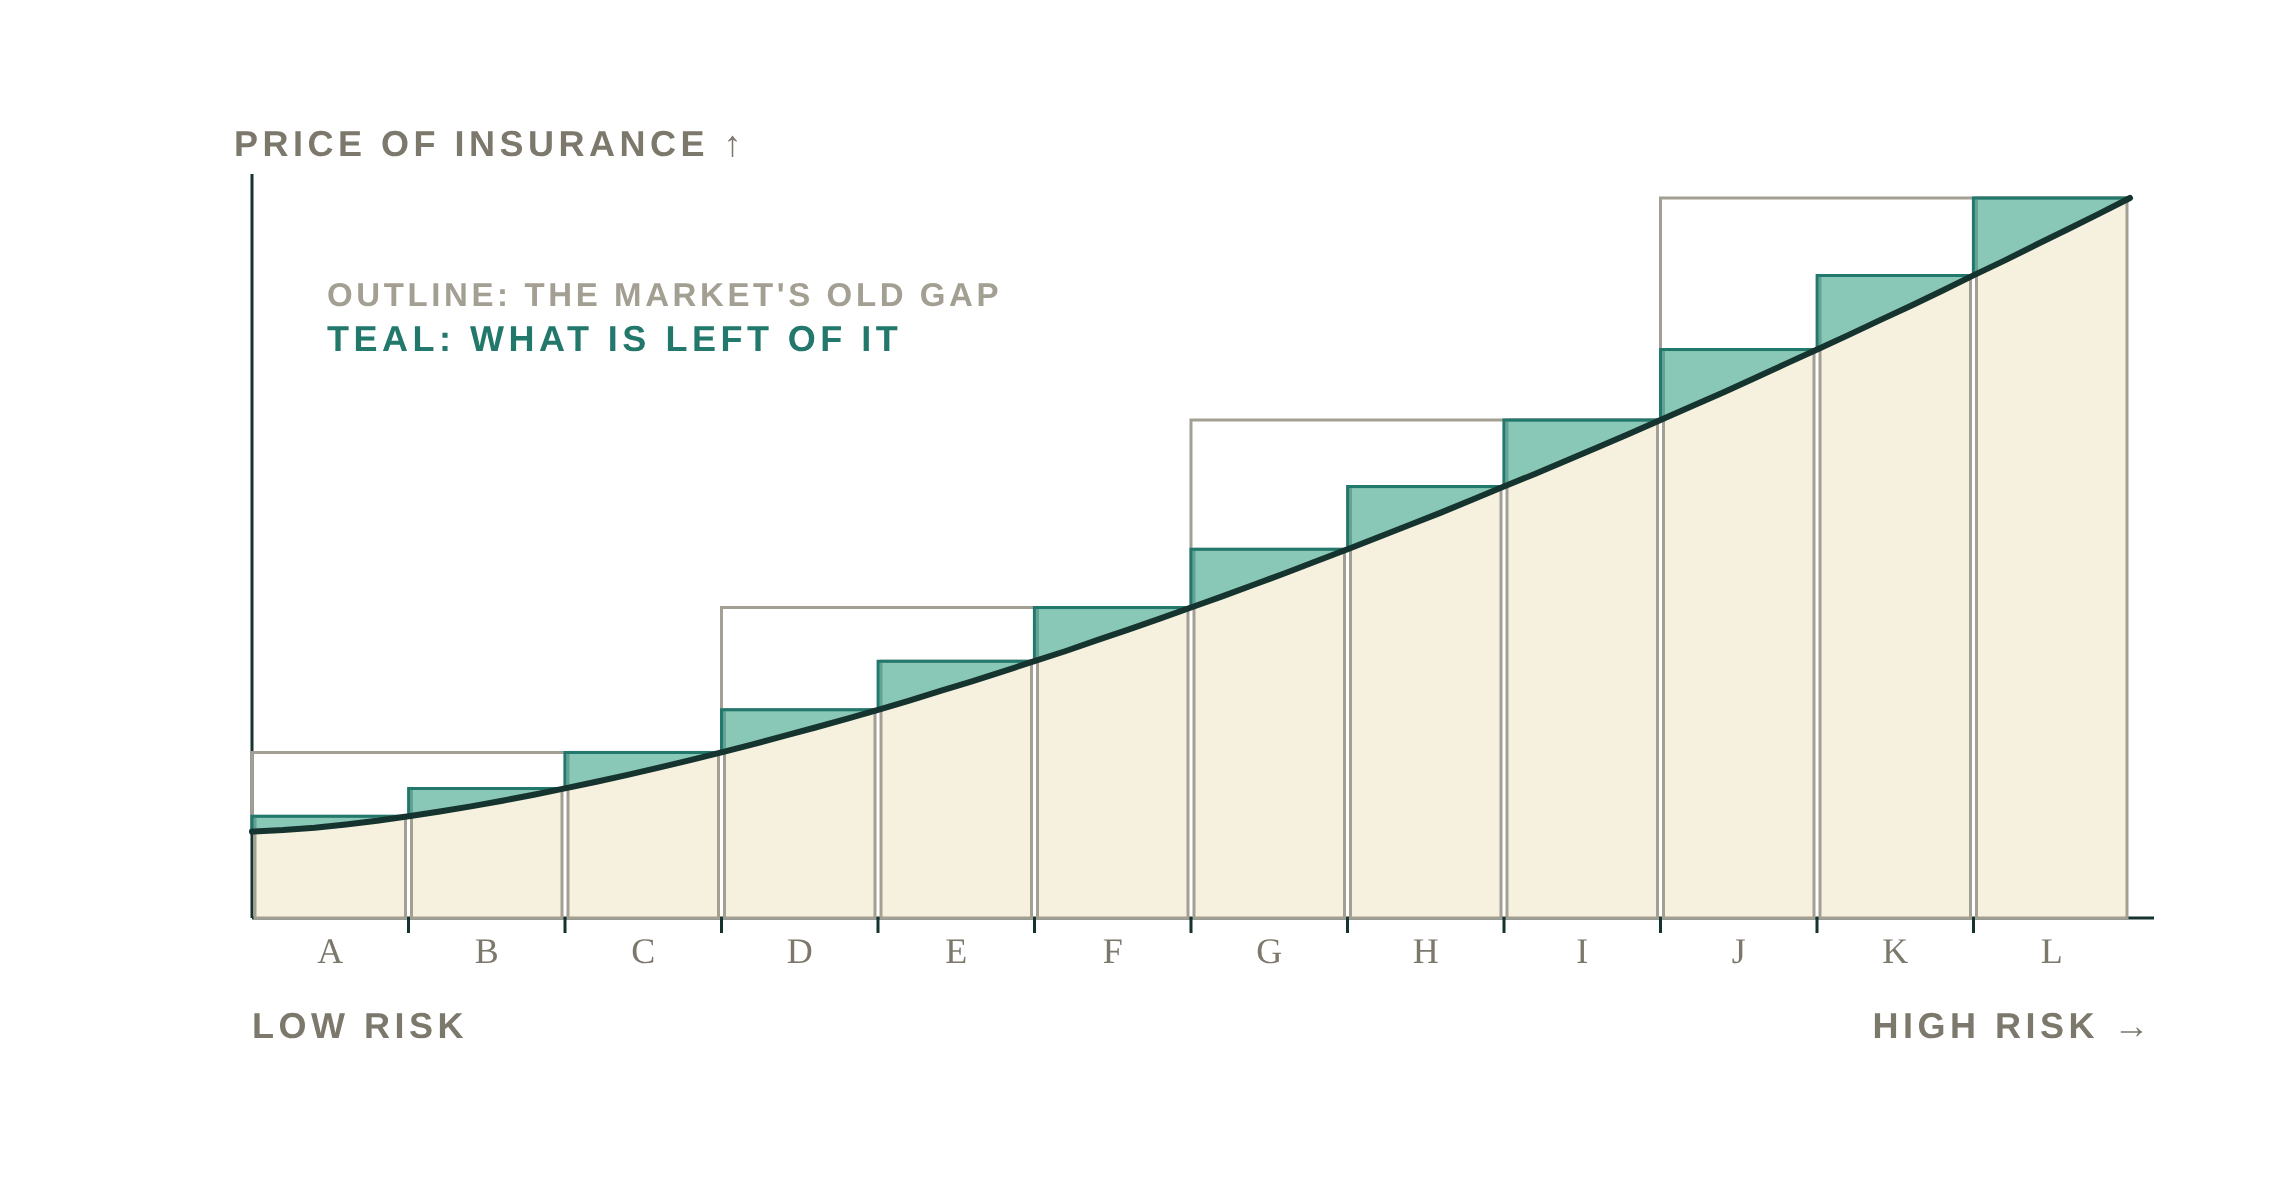
03 · What Friend does
Friend makes the buckets smaller.
Read forty signals, not three, and four bands become twelve. The old overpayment is left in outline; the teal is what remains, about two thirds smaller.
|
|
3
Signals the market reads
|
40
Signals Friend reads
|
68%
Less premium paid above true risk
|
Source: Friend Analytico, The Buckets explainer. Illustrative example: curve, bands and shaded areas are drawn to explain the idea, axes unitless on purpose, area reduction computed from the curve shown. Not a measurement or a quote.
|
|
THE FRIEND READ
Here is the part that matters for your business, not the chart. If your band is priced for its worst member and you are its best, the overpayment is yours, and you pay it every year without ever seeing a line item for it. Say the bucket overcharges a well-run shop by eight points on a $9,000 policy: that is about $720 a year funding the neighbor who never fixed the stairs. Reading more signals is how that money stops leaving, and a captive is how it comes back. The buckets will not disappear. Friend just makes them small enough that running a tight shop finally shows up in the price.
|
FRIEND ANALYTICO · THE BUCKETS (FRIENDANALYTICO.COM/BUCKETS) · FIGURES ILLUSTRATIVE
|
THE JARGON, TRANSLATED
Class rating
|
How a carrier assigns your business to a rate class: a code for your industry, tied to a filed rate per unit of exposure. It is the formal machinery behind the bucket, and the reason two very different shops in the same class get the same price.
|
|
ALSO THIS WEEK · THE BRIEFS
|
THREE DEVELOPMENTS
|
|
|
02
FIG.
|
DISTRIBUTION
/ AUTOMATION
· UNITED STATES
TECHCRUNCH · OUTMARKET AI · 28 SEPTEMBER 2026
Outmarket AI raised $34.5 million at a $335 million valuation, four months after its $17 million Series A, to automate the paperwork behind commercial insurance. The platform now runs in more than 300 agencies, a quarter of them top-100 firms, and handles application forms and document review across 250-plus coverage types. The founder's framing is the point: 95% of US insurance is still sold by human agents, through a process he calls very manual. The cost of underwriting a small account by hand is the same reason it never got read closely.
|
|
THE FRIEND READ
A broker can spend two hours rekeying and chasing one small-commercial submission, call it $120 of loaded labor, on an account whose whole commission is a few hundred dollars. That math is why the small account has always been quoted fast and priced rough. Push the cost of looking toward zero and the excuse for the bucket goes with it. The question for an operator is the plain one: when the carrier can finally afford to read your business, do your numbers reward the reading, or not?
|
|
|
03
FIG.
|
DISTRIBUTION
/ E&S
· UNITED STATES
BUSINESS INSURANCE · AXA XL · 30 SEPTEMBER 2026
AXA XL will begin writing new excess-and-surplus-lines casualty business through a dedicated carrier, AXA XL Excess & Surplus Lines Insurance, in early 2027, with property to follow, all of it placed through wholesale brokers only. E&S is the market for risk a standard filed rate cannot absorb, and it has swelled: US surplus-lines premium hit a record last year and ran to $47.6 billion in the first half of 2026, per the Wholesale & Specialty Insurance Association, even as growth cooled to 2.8%. More business is being routed to the aisle where each risk is priced on its own terms.
|
|
THE FRIEND READ
When a restaurant with a fryer, a patio heater, and three prior slip claims gets non-renewed by its standard carrier, this is where it lands, and the price reflects the file rather than the territory. That cuts both ways. The careful operator pushed into E&S often finds its premium falls once a human actually reads the account, while the careless one pays for what the reader finds. On a $12,000 package the spread between the bucket rate and the read rate can run $3,000 or more. The aisle keeps growing because the standard shelf keeps deciding it cannot see well enough to carry the risk.
|
|
|
04
FIG.
|
CYBER
/ UNDERWRITING
· UNITED STATES
REINSURANCE NEWS · KYND · 30 SEPTEMBER 2026
KYND launched a tool that lets a cyber underwriter detect the AI technologies on a company's external digital footprint from a single domain, with no input from the company: chatbots, generative-AI apps, AI in marketing and commerce stacks, AI crawlers. The reason is disclosure. Firms adopt AI faster than they report it, and proposal forms miss what the business itself may not fully track. IBM's latest breach study found one in five organizations reported a breach tied to this shadow AI last year, and that heavy shadow-AI users carried breach costs about $670,000 higher than those with little or none.
|
|
THE FRIEND READ
Notice the direction. The underwriter stopped asking the business to describe itself and started reading the business directly, because the self-description had stopped being reliable. A small firm running three unsanctioned AI tools now looks different, and prices differently, from the one running none, and neither has to fill in a longer form to show it. On a $1,500 small-business cyber policy the signal that used to be invisible is turning into a line item. The readable facts about how you actually operate are becoming your price, in cyber first because that is where they are easiest to see.
|
|
THE WEEK, IN ONE LINE
The Buckets is the picture; the three briefs are the market walking toward it. Every time somebody pays to look closer, the bands get finer and the well-run stop subsidizing the careless. Nothing about the businesses changed. Somebody looked closer.
|
ASK FRIEND
Opens in October
|
Reply to this note with the insurance question you would be slightly embarrassed to ask your broker. The first issue of every month, starting this month, answers one of them in plain language. No names, no follow-up sales call, and if the honest answer is "nobody knows," we will say that.
|
ON THE CALENDAR
|
EARLY NOVEMBER
|
Ivans releases its October renewal index. We are watching one line: whether small-commercial BOP finally cools below five points, or whether Main Street keeps paying up while the market calls itself soft.
|
|
MID-NOVEMBER
|
CIAB's third-quarter survey. The question we keep asking: does the small account get more than a rounding error this time?
|
|
EARLY 2027
|
AXA XL E&S begins writing casualty. Watch how much mid-market risk the standard shelf decides it would rather send down the wholesale aisle.
|
SOURCES
|
FRIEND IS RAISING A SEED ROUND
We're building the risk-intelligence layer for small-business insurance.
The Green, Yellow, and Red score that lets the discount reach the deli. If you want the full plan, or you just want to learn more, reach us at
newcombe@friendanalytico.com, or simply reply to this note. Whether you are thinking about investing or only want to learn more, either is welcome.
|
|
FRIEND.
Clarity is the product.
EVERY BUSINESS IS A CROSS-SECTION
· CLARITY IS THE PRODUCT.
A weekly read on small-business insurance from Friend, which builds the score that tells a careful operator from a careless one. You're getting it because you're close to us; if we've read something wrong, reply and say so, the more brutal the feedback the better.
NEW YORK · 2026 · WRITTEN BY NEWCOMBE, FOUNDER OF FRIEND · YOU'RE RECEIVING THIS AS A FRIEND OF FRIEND, INVESTOR, CLIENT, OR FELLOW TRAVELER.
FORWARD IT TO A FRIEND OF FRIEND. THEY CAN REPLY TO BE ADDED.
|
|