|
FRIEND OF FRIEND
/ THE WEEKLY
|
VOL. 10
· 2026
|
RISK-INTELLIGENCE FOR SMALL-BUSINESS INSURANCE
· VOL. 10, WEEK OF OCTOBER 12, 2026
· 5-MINUTE READ
A captive is an insurance company you build to insure yourself. The only hard part is who you let in.
|
LAST TIME WE SAID
|
Vol. 09: in a soft market the scarce asset is not capital, it is a clear view of the single risk, and the discount reaches the small account only once it can be priced one at a time. A captive is what that clear view lets a careful operator do next: stop renting the risk and own it.
|
|
FROM THE DESK
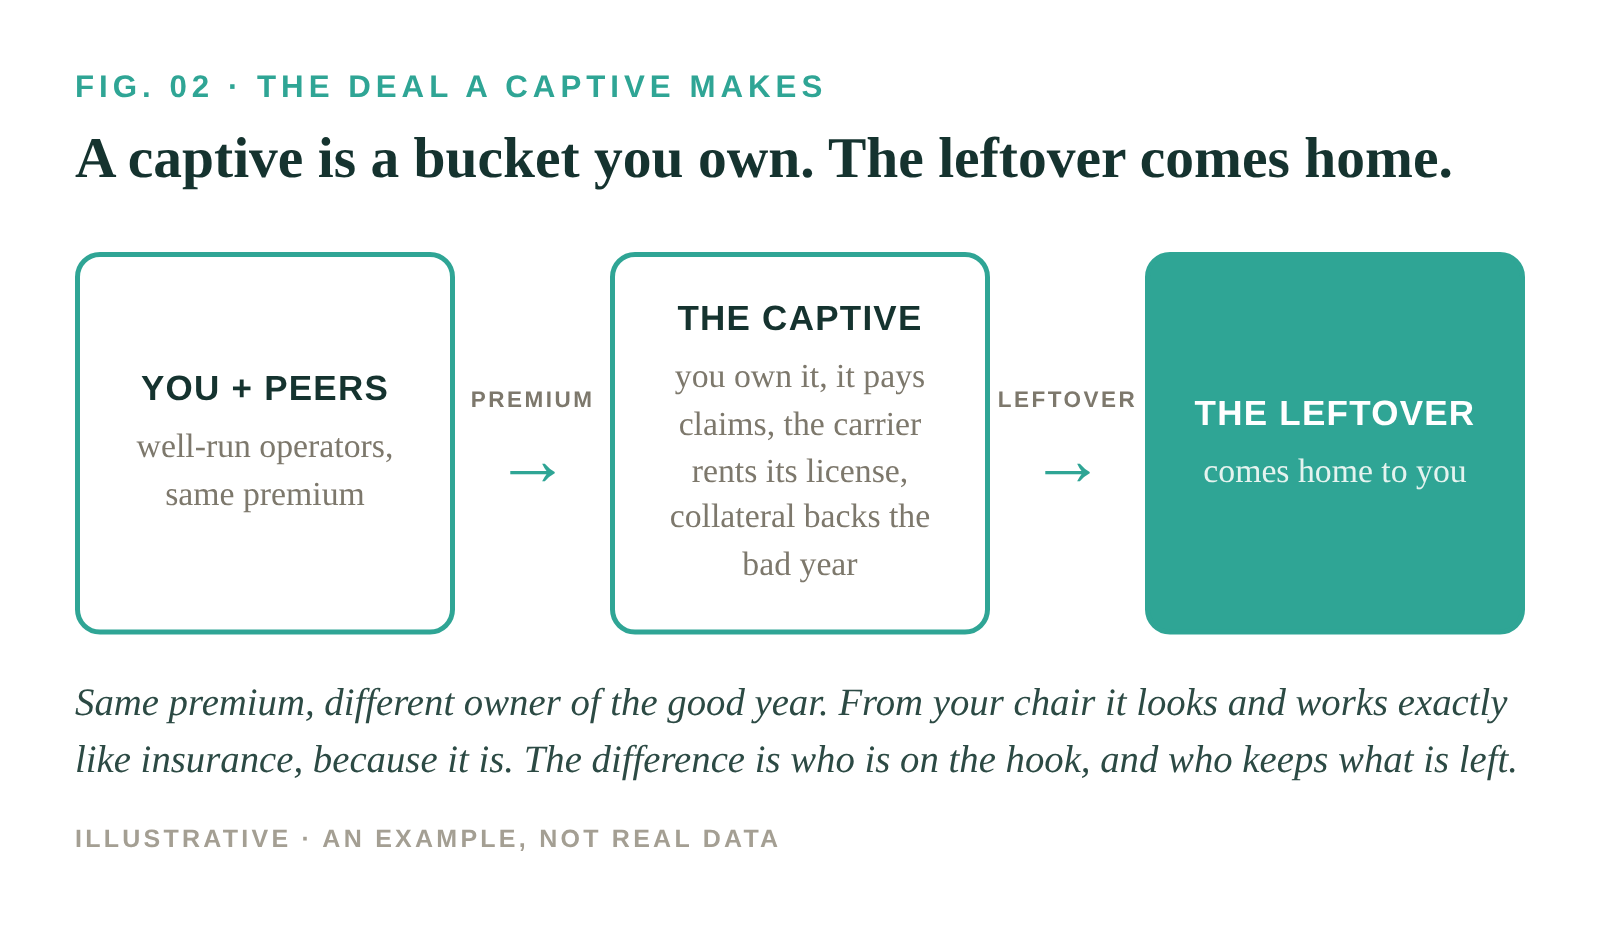
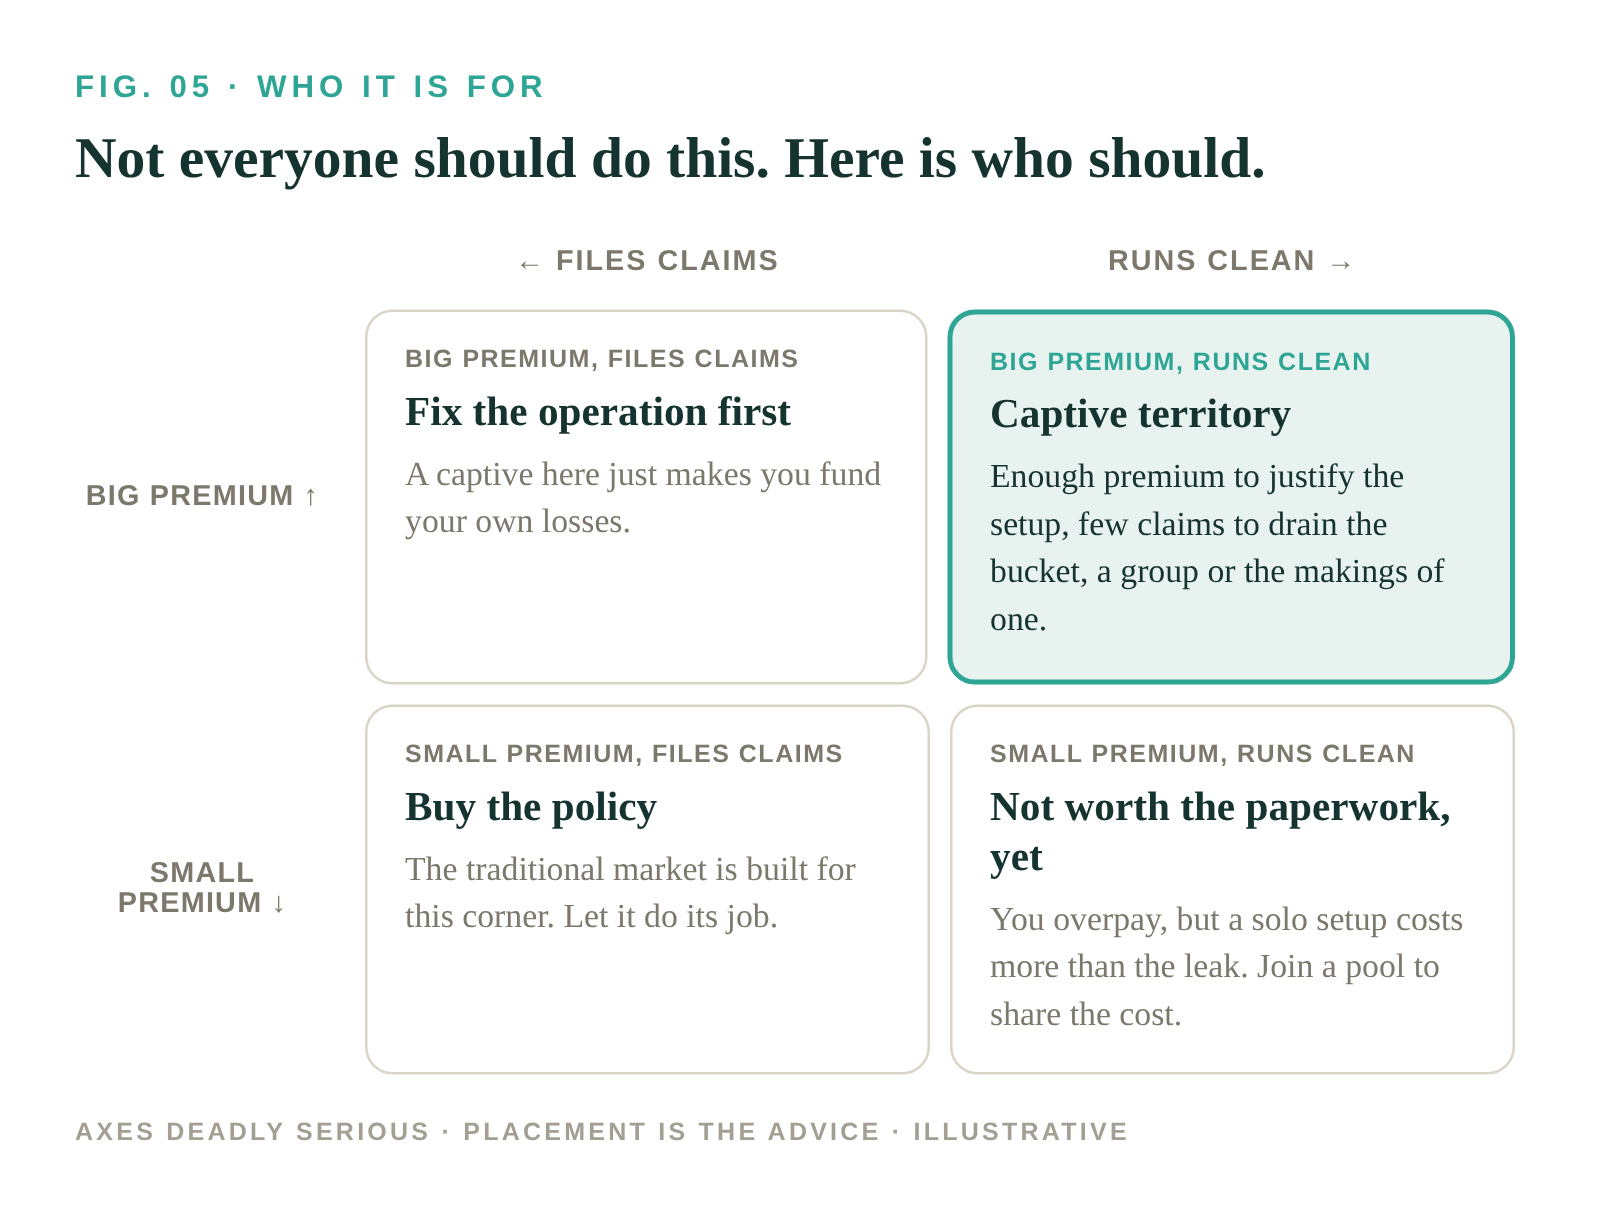
This week, we're talking captives. A captive is an insurance company that you own for yourself. In a captive, it's your premium that funds your own claims and the money left over in a good year comes back to you instead of staying with a traditional insurance carrier. For a small business that runs clean operations and rarely files a claim, a captive is not a tax trick or a quirky loophole, it is a way to stop subsidizing everyone else's losses and keep what your own operational discipline earns. Most operators have never seriously looked at self-insurance because captives have been priced and sold for the big guys with the complex risks. Nobody could tell, at the small end, which businesses actually belong in a captive. That is the gap in knowledge Friend is built to close: our models are meant to identify the prudent operators that a captive arrangement would genuinely benefit, and then we help the right firms stand one up. If you run a tight shop, a captive is a tool worth understanding, and the panels below explain it in plain language.
Regards,
NEWCOMBE · FOUNDER, FRIEND · NEW YORK
BY THE NUMBERS
|
7,000+
Captives worldwide, holding over $80 billion in annual premium
|
$6.5B
US group-captive premium, about 6.5% of the commercial casualty market
|
98-99%
Member retention in group captives, far above the standard market
|
707
Active captives in Vermont alone, with 51 licensed in 2025
|
|
THIS WEEK · THE ONE TO DISCUSS
|
THE EXPLAINER · IN SIX PANELS
|
|
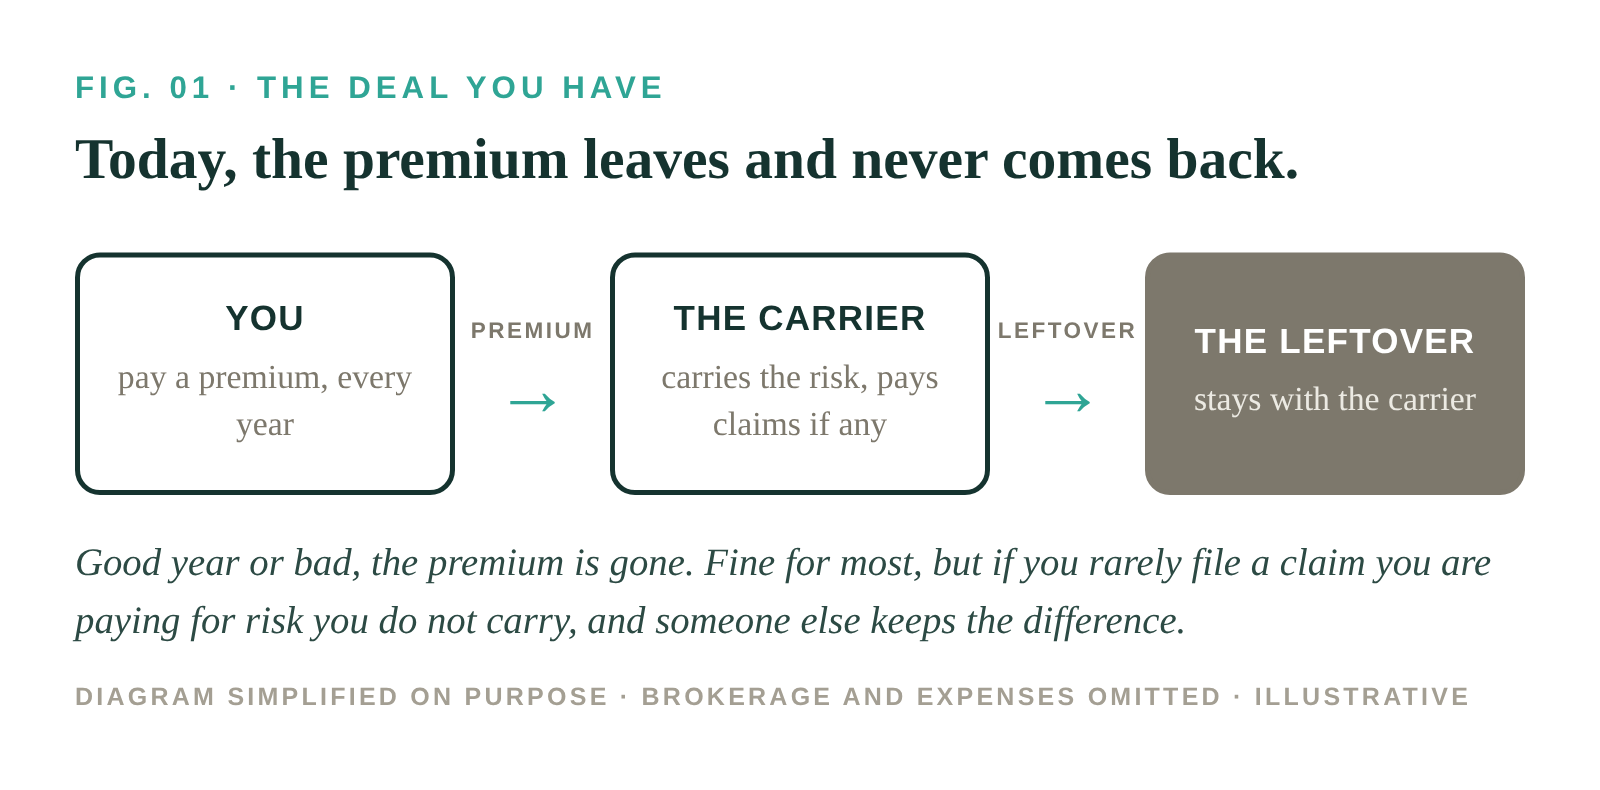
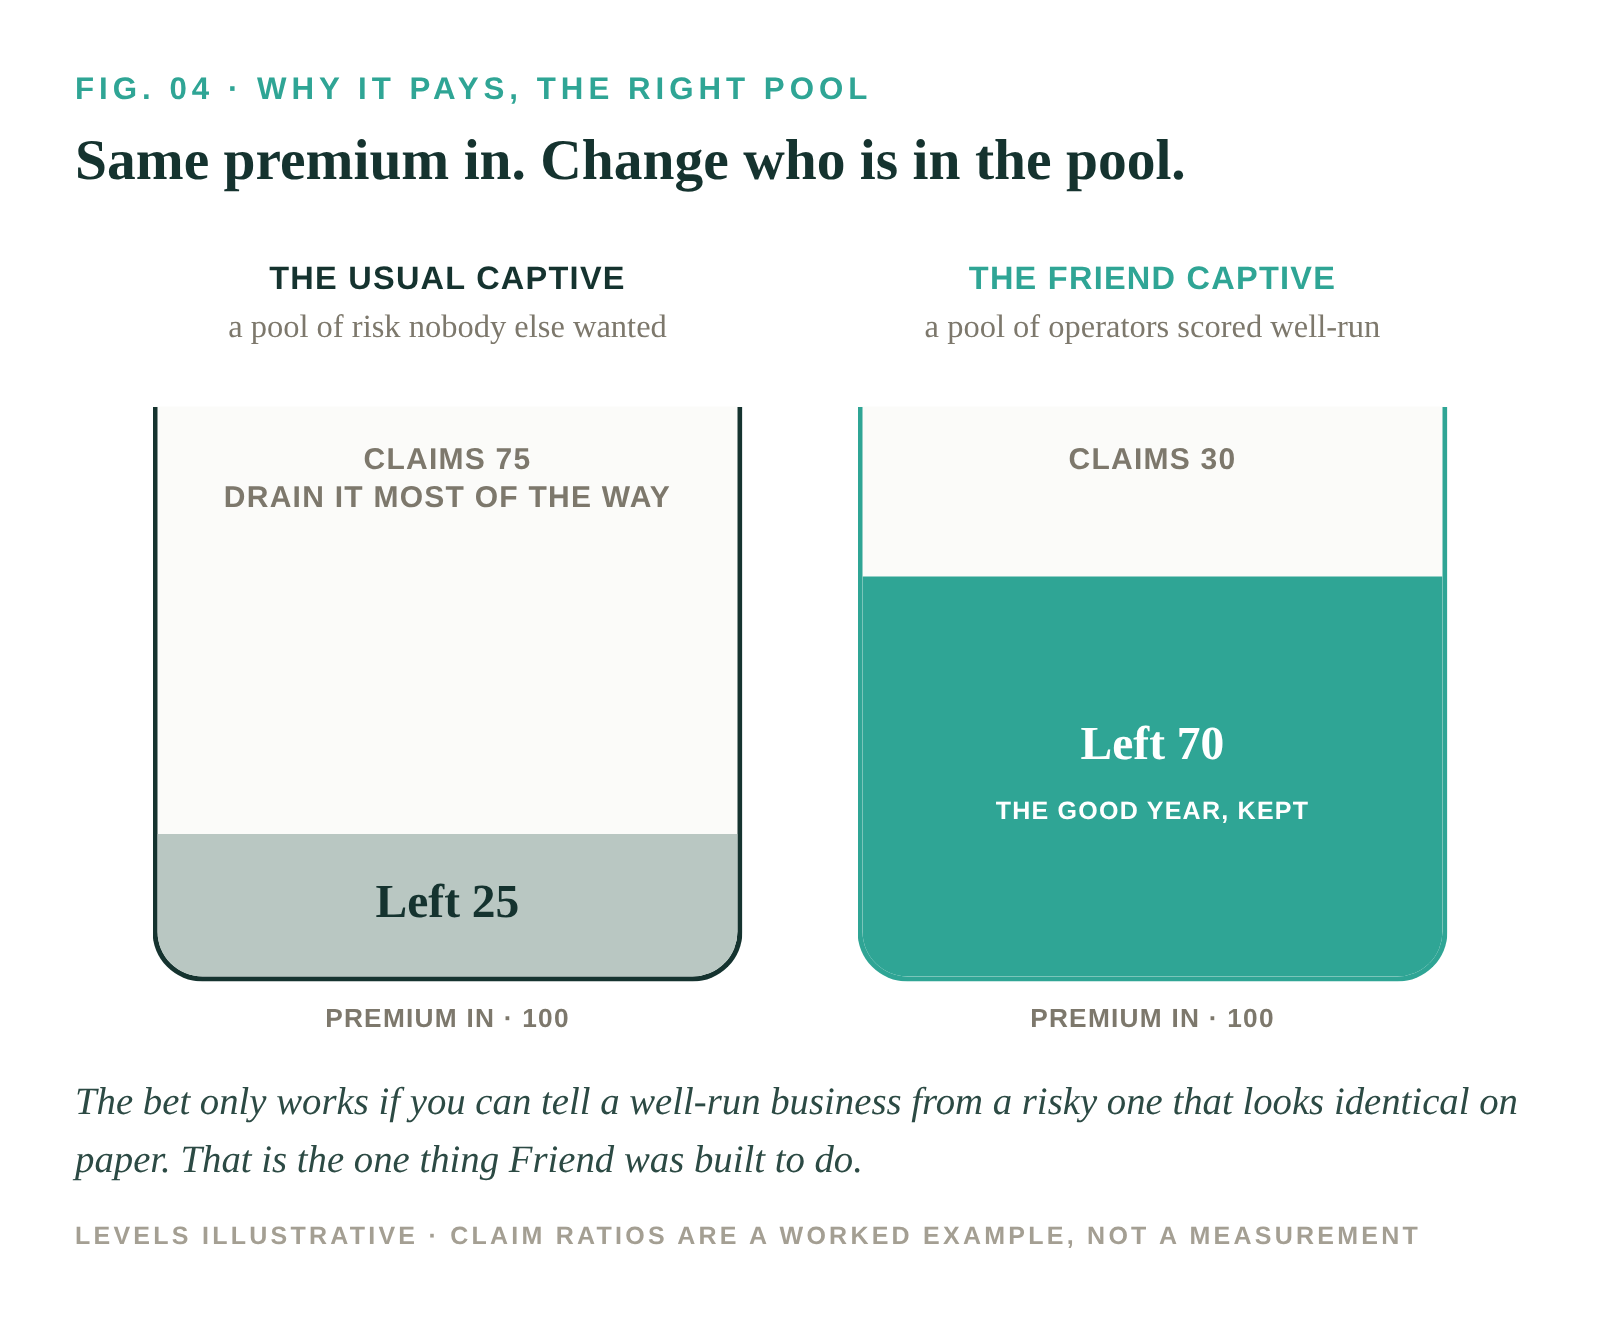
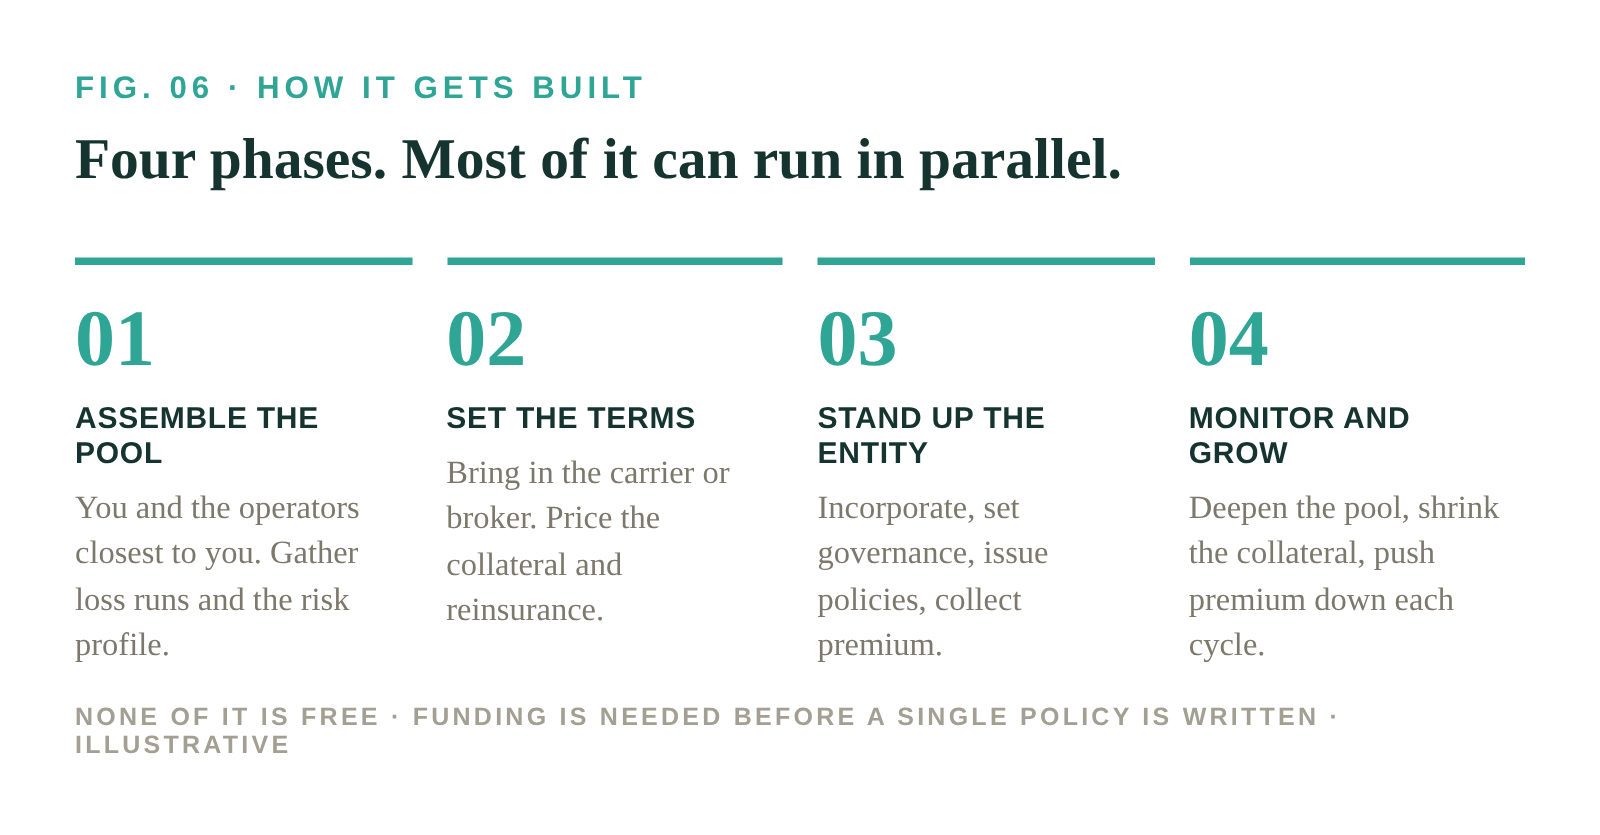
Most businesses rent their insurance: the premium leaves every year and never comes back. A captive is the structure that lets a well-run operator own it instead and keep the good year. The only hard part is being sure everyone else in the pool is as careful as you are. Read it in six panels.
|
|
THE FRIEND READ
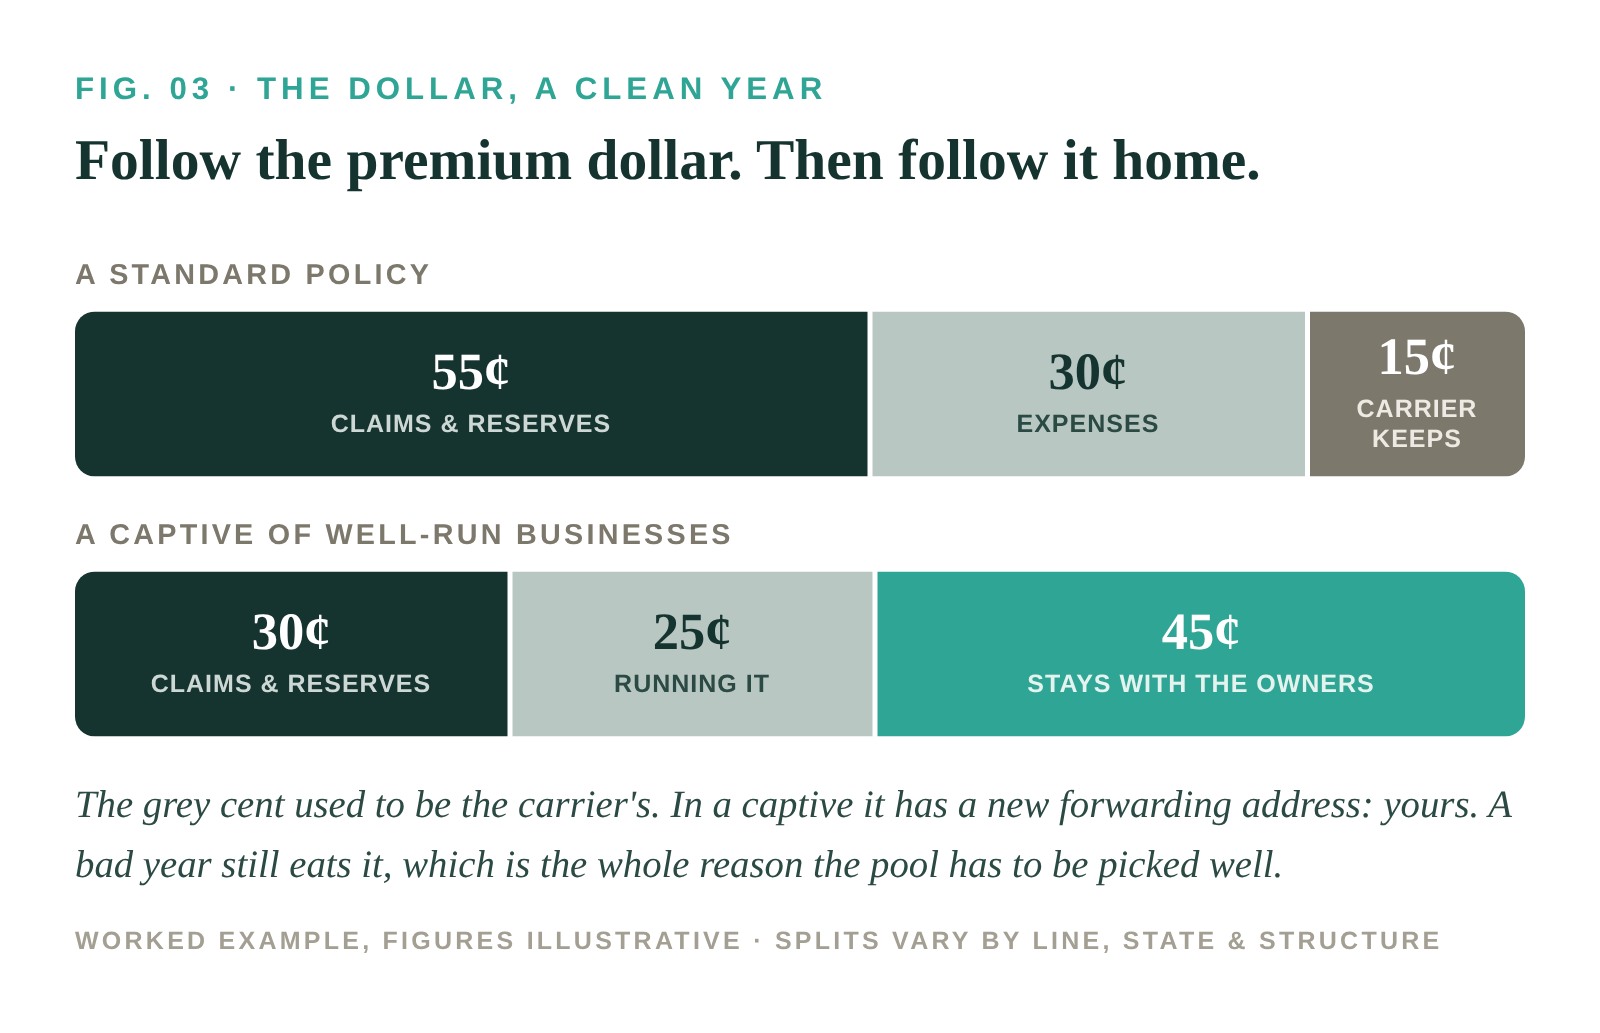
On the illustrative clean-year dollar, the move is 15 cents to 45: the carrier's keep becomes yours. Nothing about that is magic, and nothing about it is free, because a bad year still eats the leftover and sometimes the collateral behind it. The whole thing turns on the pool, and the pool turns on one question nobody can answer at the small end: who is actually well-run. That is the question the score we are building exists to answer, which is why the captive is the structure Friend points at next.
|
FRIEND · THE CAPTIVE, AN EXPLAINER · FRIENDANALYTICO.COM/CAPTIVE
|
THE JARGON, TRANSLATED
Collateral
|
The money a captive's owners post, on top of premium, to stand behind a bad year that premium alone cannot cover. It is the catch said up front: a captive rewards the well-run by asking them to back their own risk with real money, not just a signature.
|
|
ALSO THIS WEEK · THE BRIEFS
|
THREE DEVELOPMENTS
|
|
|
02
FIG.
|
INSURTECH
/ AI UNDERWRITING
· UNITED STATES
REINSURANCE NEWS · LEDGEBROOK · 7 OCTOBER 2026
On October 7 Ledgebrook, an AI-native specialty insurer, raised $200 million co-led by Allianz X and Rockefeller Capital Management and signed a multi-year reinsurance deal with Allianz Re. Its Blackbird platform reads each submission, classifies the risk and sets a technical price, often in hours rather than weeks, while an experienced underwriter still makes the final call. The firm is on track to pass $1 billion in cumulative premium written.
|
|
THE FRIEND READ
Even the most AI-native carrier in the market draws the line in the same place: the machine does the reading and the first-pass price, a person signs the number. The mechanics are nearly free now, and the judgment of whether a specific risk is good stays scarce and human. On a small-commercial account quoted in seconds, the few dollars of that judgment are still what move the price.
|
|
|
03
FIG.
|
PRICING TECH
/ AI AGENTS
· GLOBAL
FINTECH GLOBAL · EARNIX · 6 OCTOBER 2026
Earnix, an insurance-decisioning software firm with more than 25 years in pricing and rating, launched Agent Hub, production-ready AI agents for pricing, underwriting and modeling that run inside its orchestration system. The agents gather information and carry out tasks in a governed setting, but Earnix says people remain involved to supervise, review and retain control over the significant decisions. The launch drew more than 350 senior insurance figures to its London event.
|
|
THE FRIEND READ
The incumbent that has spent a quarter-century automating rate-making draws the same line as the newcomer. Agents do the gathering and the math; a person signs what goes on the policy, because a wrong one lands on the book, not the tool. On a $3,000 small-commercial renewal the quote can be ready in seconds, and the judgment about whether this is the careful shop still sets the price.
|
|
|
04
FIG.
|
COVERAGE GAP
/ AFFORDABILITY
· UNITED STATES
INSURANCE JOURNAL · HIPPO EXTREME WEATHER REPORT · 7 OCTOBER 2026
Hippo's third annual extreme-weather survey of 1,047 US homeowners found half paid out of pocket for weather damage over the past three years, 21% of them $2,000 or more, and nearly a quarter still carry debt from it. Thirty-nine percent had wrongly believed the damage was covered, and 55% could not recall their own deductible. This is personal lines, but the mechanism reads straight across to the small-commercial package a shop or a restaurant buys once and rarely rereads.
|
|
THE FRIEND READ
The gap between what a buyer thinks the policy covers and what it actually holds is a pricing problem wearing a coverage mask. When price is the only thing competing, the quiet way to defend a margin is a higher deductible and an exclusion nobody notices until a claim. A restaurant owner with a $6,000 package who finds the water-damage sublimit is $10,000 and not $100,000 learns the lesson these homeowners did.
|
|
THE WEEK, IN ONE LINE
Owning your own risk is a good trade only if the pool is full of operators as careful as you are, which is why a structure that is already a $6.5 billion market at the top still comes down to the one question nobody can answer at the bottom: who is actually well-run.
|
ASK FRIEND
Opens in October
|
Reply to this note with the insurance question you would be slightly embarrassed to ask your broker. The first issue of every month, starting this month, answers one of them in plain language. A captive question counts. No names, no follow-up sales call, and if the honest answer is "nobody knows," we will say that.
|
ON THE CALENDAR
|
EARLY NOVEMBER
|
Ivans releases its October renewal index. We are watching whether small-commercial rates keep rising, because the longer they do, the more a captive starts to pencil for the careful operator.
|
|
MID-NOVEMBER
|
CIAB's third-quarter survey. The question we keep asking: does the small account get more than a rounding error, or enough of a squeeze to make owning its own risk worth the paperwork?
|
|
YEAR-END
|
The domiciles report full-year captive formation tallies. We are watching whether cell and group structures, the on-ramps for smaller operators, keep outpacing standalone captives.
|
SOURCES
Friend, The Captive, an explainer (figures illustrative) ·
Ledgebrook secures $200m, Reinsurance News, 7 Oct 2026 ·
Earnix unveils Agent Hub, FinTech Global, 6 Oct 2026 ·
Hippo extreme-weather report, via Insurance Journal, 7 Oct 2026 ·
Group captives, Business Insurance, 10 Mar 2026 ·
Vermont captive results, Vermont DFR, 21 Jan 2026
|
FRIEND IS RAISING A SEED ROUND
We're building the risk-intelligence layer for small-business insurance.
The Green, Yellow, and Red score that tells a careful operator from a careless one, and the thing that finally lets a small business own its own risk. If you want the full plan, or you just want to learn more, reach us at
newcombe@friendanalytico.com, or simply reply to this note. Whether you are thinking about investing or only want to learn more, either is welcome.
|
|
Clarity is the product.
EVERY BUSINESS IS A CROSS-SECTION
· CLARITY IS THE PRODUCT.
A weekly read on small-business insurance from Friend, which builds the score that tells a careful operator from a careless one. You're getting it because you're close to us; if we've read something wrong, reply and say so, the more brutal the feedback the better.
Why you're reading this, in full →
NEW YORK · 2026 · WRITTEN BY NEWCOMBE, FOUNDER OF FRIEND · YOU'RE RECEIVING THIS AS A FRIEND OF FRIEND, INVESTOR, CLIENT, OR FELLOW TRAVELER. FORWARD IT TO A FRIEND OF FRIEND. THEY CAN REPLY TO BE ADDED. ·
READ ON THE SITE ·
EVERY ISSUE
|
|